Section 85 Rollover: A Tax-Deferred Strategy for Canadian Business Owners

If you’re a Canadian business owner, there may come a time when you need to move assets into a corporation—whether you’re incorporating your sole proprietorship, setting up a holding company, or reorganizing your existing business for tax or estate planning purposes. The challenge? Such transfers can trigger significant immediate taxes on any gains built up over time.

That’s where Section 85 of the Income Tax Act, commonly known as the Section 85 rollover provision, comes in. This election allows a taxpayer to move eligible assets into a taxable Canadian corporation on a tax-deferred basis, meaning you won’t have to pay tax right away on any built-up gains. Instead, you can push that tax liability into the future, giving you more flexibility and control over your cash flow.

This strategy is especially valuable for sole proprietors who are ready to incorporate and take advantage of benefits like lower small business tax rates and limited liability. It’s also widely used by existing corporations that want to reorganize their assets or transfer property into a holding company as part of a broader tax or estate plan.

In this article, we’ll walk through how the Section 85 rollover works, who qualifies, the rules you need to follow, and some common examples to help you see it in action.

What Is a Section 85 Rollover?

Generally, under subsection 69(1), when a taxpayer disposes of property to a non-arm’s length party, the proceeds of disposition are deemed to equal the fair market value of the property. For example, when you transfer your property as a sole proprietor to a corporation and the property in question has accrued gains, it will be transferred at fair market value, which could create a large tax bill.

A Section 85 rollover is a tax election under the Canadian Income Tax Act that allows a taxpayer (the transferor)  to transfer eligible assets to a taxable Canadian corporation (the transferee) in exchange for shares and other non-share consideration. By transferring assets under Section 85, the transferor can avoid triggering immediate capital gains tax at the time of transfer.
Section 85 Rollover

Purpose of the Section 85 Rollover

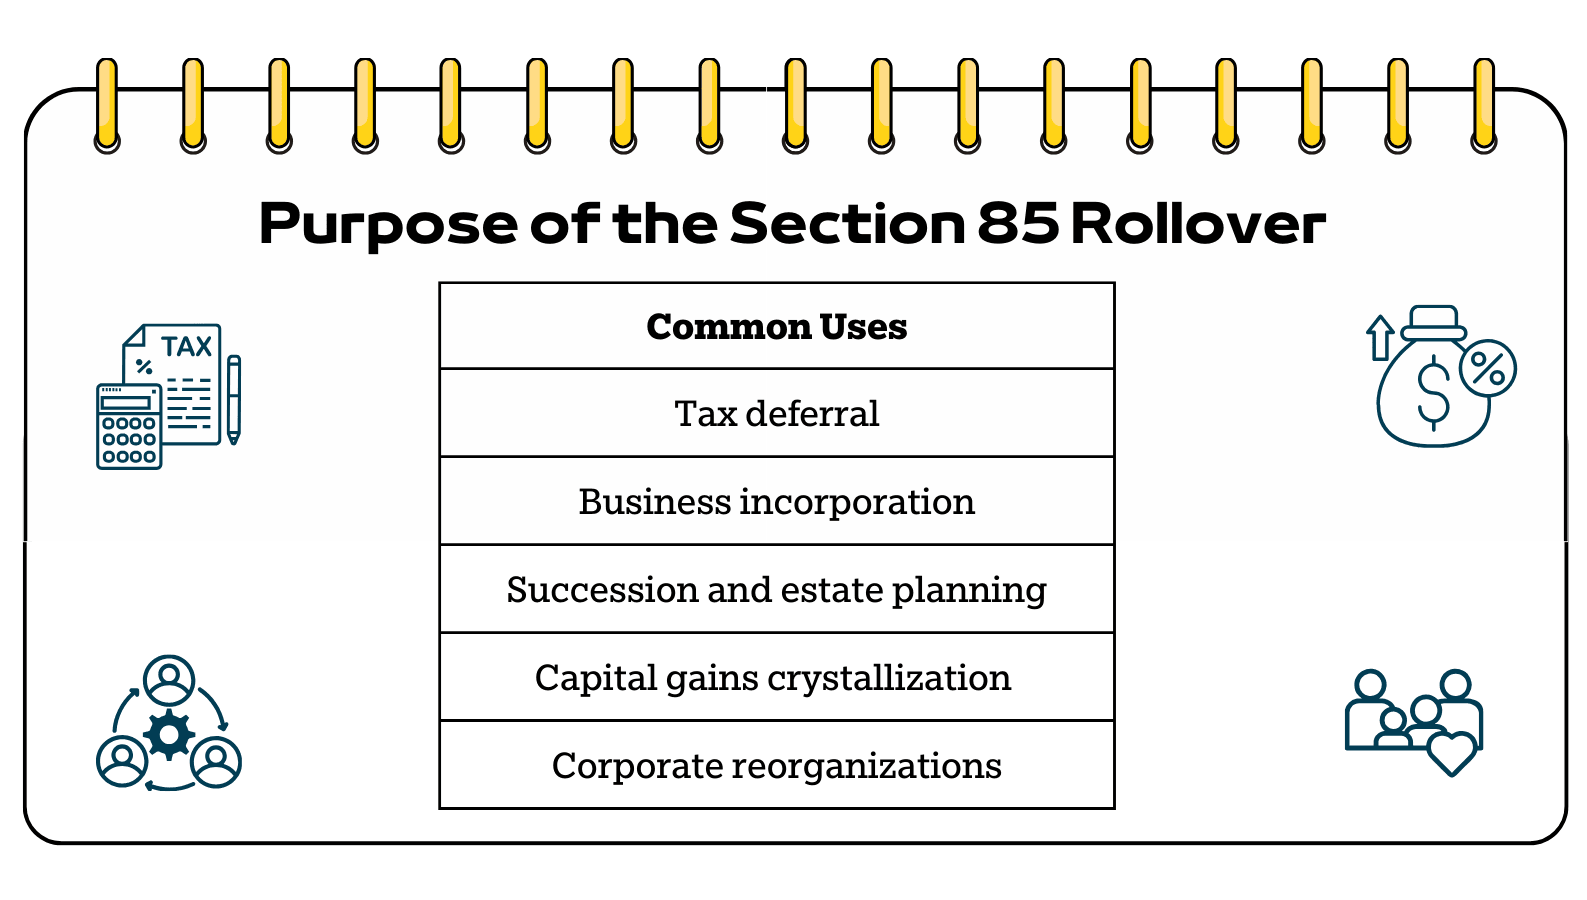
The Section 85 election is a cornerstone of Canadian tax planning and the primary purpose is tax deferral. As such, the rollover exists to provide flexibility and tax efficiency in business structuring. Without it, every time assets are moved into a corporation, owners would face immediate taxes on any appreciation in value—even though nothing was actually sold for cash. Its primary purpose is to enable tax-efficient transfers of property to a corporation. Common uses include:

  • Business incorporation – Transfer assets to your new corporation without immediate tax consequences.
  • Succession and estate planning – Reorganize family business ownership for smoother generational transfer.
  • Capital gains crystallization – Trigger specific gains strategically to use exemptions or offset losses.
  • Corporate reorganizations – Move assets between related companies as part of restructuring.
  • Tax deferral – Shift income-generating property into a corporation to benefit from lower corporate tax rates.

However, while the Section 85 can result in deferral of tax, the purpose is not to eliminate or reduce the overall tax liability.
Section 85 Rollover

Requirements for a Section 85 Election

To successfully use a Section 85 rollover, there are some key conditions that must be met:

  1. Eligible Transferor  – The transferor must be an individual, corporation, or trust. The transferor can also be a partnership, provided that all partners are resident in Canada. . 
  2. Eligible Transferee – The transferee must be a taxable Canadian corporation. In other words, the receiving entity has to be incorporated in Canada and subject to Canadian tax rules. This ensures that the rollover can’t be used to shift assets outside Canada without immediate taxation.
  3. Eligible vs. Non-Eligible Assets - Not every type of property qualifies for a Section 85 rollover. 

Eligible property includes:

  • Capital property (depreciable and non-depreciable) – such as equipment, buildings, land, shares etc. 
  • Certain inventory (excluding real property inventory)
  • Canadian and foreign resource property

Non-eligible property includes:

  • Real property held as inventory (i.e land bought for resale by a developer). 
  • Prepaid expenses
  • Personal-use property
  • Accounts receivable 
  1. Shares consideration – The consideration must include at least one share of the corporation. Non-share considerations (“boot”) may also be included but it cannot exceed the elected amount/cost of the property transferred. If non-share consideration exceeds the cost/elected amount, a gain will be triggered to that extent. Common non-share consideration includes cash, promissory note or assumption of liabilities.  
  2. Joint election filing – Both the transferor and transferee must file Form T2057 by the earlier of the tax filing deadline of the transferor and transferee for the year in which the transfer took place. 
  3. Elected amount limits – The elected amount is the transfer price jointly chosen by the transferor and the corporation. This “elected amount” becomes the transferor’s proceeds of disposition and the transferee’s (purchaser’s) cost of the asset. The elected amount must fall within between these two general limits:
    • Lower limit: cannot be less than the fair market value of the non-share consideration (“boot”) received by the transferor.  
    • Upper limit: cannot exceed the fair market value of the property transferred.

Special Limits:

  • For inventories and non-depreciable capital property, the lower limit cannot be less than the lesser of:
    • FMV of property 
    • Cost amount of the property transferred.
  • For depreciable properties, the lower limit cannot be less than the lesser of:
    • FMV of property
    • Cost amount of the property transferred
    • Undepreciated Capital Cost (UCC)

For in-depth technical rules on elected limits, see CRA’s Income Tax Folio S4-F5-C1.

Typical Scenarios and Examples

Example 1: Incorporating a Sole Proprietorship and Transfer of Assets

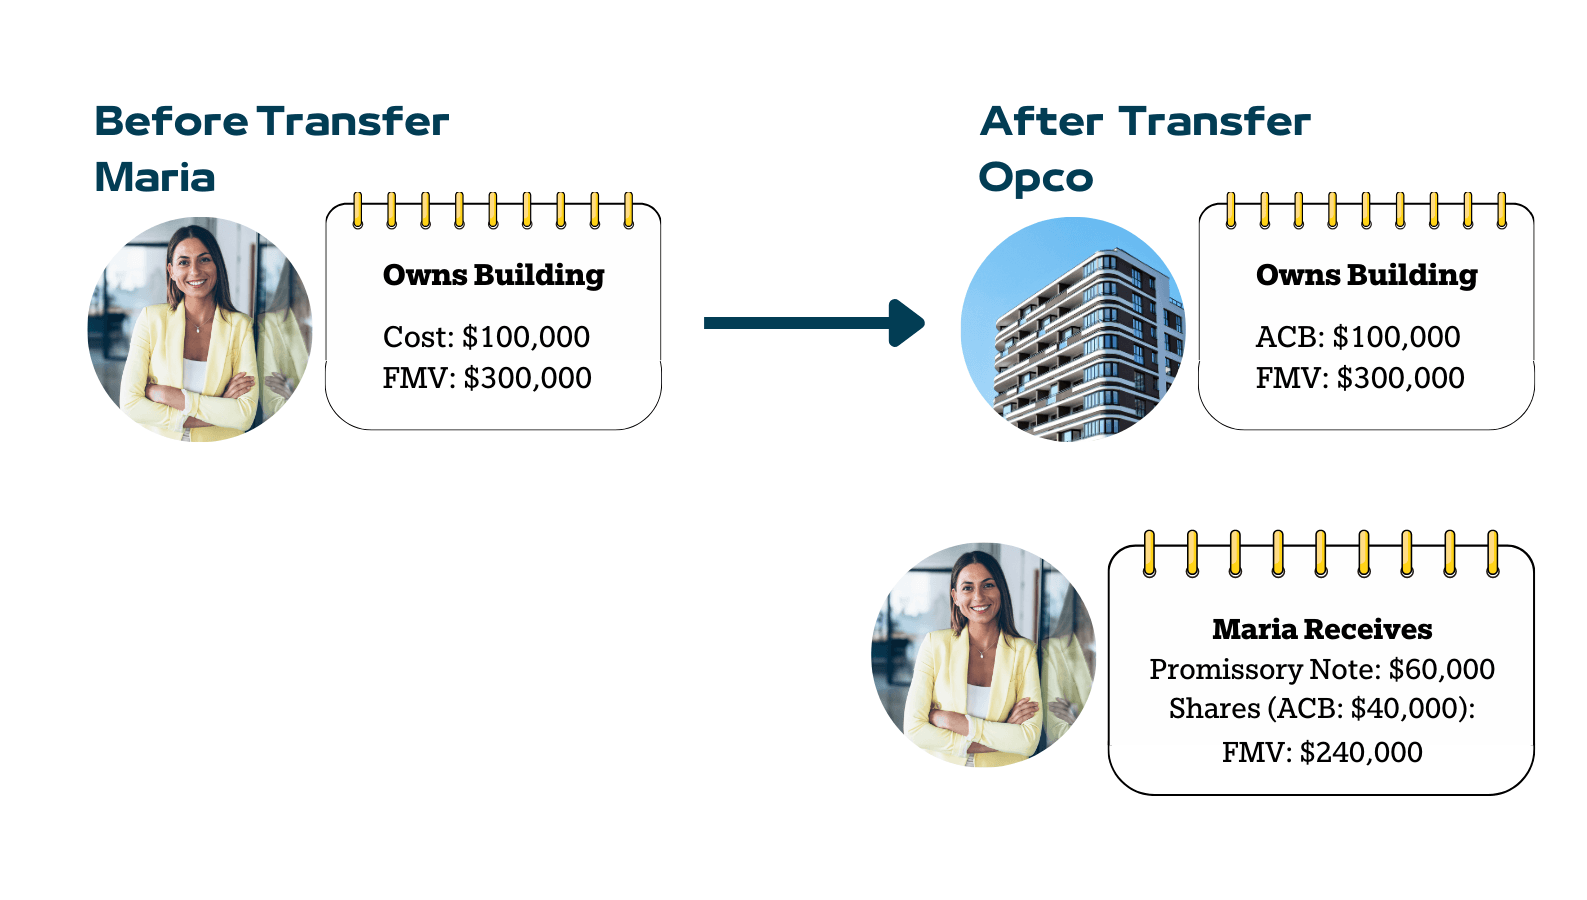
Maria runs business as a sole proprietor and owns building with:

  • Original cost (cost): $100,000
  • Fair market value (FMV): $300,000

Maria wants to transfer the building into her newly incorporated company (Opco) in exchange for shares and a $60,000 promissory note.

  • Without a Section 85 rollover, Maria has a capital gain in the amount of $200,000 on the building ($300,000 FMV – $100,000 cost).
  • With a Section 85 rollover, Maria and Opco can choose an elected amount anywhere between the building’s cost ($100,000) and its FMV ($300,000).
  • If Maria transfers or elects at $100,0000, Maria avoids triggering immediate capital gains tax because the transfer value equals her original cost.
  • The $60,000 promissory note (boot) reduces the adjusted cost base of the shares Maria receives. The ACB of Maria’s shares on the transfer is $40,000 (elected amount of $100,000 - $60,000 of boot or cash received). 

In this way, Maria defers her $200,000 gain until she disposes of her shares in the future.

A summary of the transaction is illustrated below:
example 1 3

How to File a Section 85 Rollover (Form T2057)

To take advantage of the Section 85 rollover, the parties must file Form T2057: Election on Disposition of Property by a Taxpayer to a Taxable Canadian Corporation and complete the following steps:

  1. Identify eligible assets for transfer
  2. Valuation – Obtain fair market valuations, especially for goodwill and real estate.
  3. Incorporate the corporation – Ensure the receiving company is properly set up with the right share structure.
  4. Draft a transfer agreement – Document the assets transferred and the consideration received. Ensure a price adjustment clause is included in the purchase agreement. 
  5. Complete Form T2057 – Both transferor and transferee must file.
  6. Meet the deadline – File by the earliest of either party’s tax filing due date.
  7. Maintain records – Keep valuations, agreements, and calculations in case of CRA review.
conclusion 1

The Section 85 rollover is one of the most valuable planning tools available to Canadian business owners. It enables you to incorporate, reorganize, or plan succession while deferring immediate tax liabilities.

That said, the rules can be complex. Proper valuations, transfer agreements, and timely filing of Form T2057 are critical. For this reason, most entrepreneurs rely on professional tax advisors to guide them.

By understanding and applying this powerful rollover strategy, you can grow and restructure your business in a tax-efficient way, deferring taxes until a more strategic time in the future.

Whether you're incorporating, restructuring, or planning for succession, our accountants can guide you through the complexities of the Section 85 rollover. As a full-service accounting firm in Hamilton , our experienced tax accountants are ready to provide the expertise and support you need. Contact us today.

If you want to learn more about other tax and accounting topics, explore the rest of our blog!


Disclaimer

The information provided on this page is intended to provide general information. The information does not take into account your personal situation and is not intended to be used without consultation from accounting/tax professionals. NBG Chartered Professional Accountant Professional Corporation will not be held liable for any problems that arise from the usage of the information provided on this page.
Are Tips Taxable in Canada? The Essential Guide to How The CRA Treats Gratuities

Are tips taxable in Canada? Yes — the Canada Revenue Agency (CRA) considers all tips and gratuities as taxable income. Whether you’re a server, bartender, hairstylist, taxi driver, or work in another service-based role, understanding how tips are taxed is essential for staying compliant and avoiding penalties while increasing your financial benefits, such as higher CPP contributions and more RRSP contribution room.

This article explains the tax treatment of direct, controlled, and declared tips, how to report them, employer and employee responsibilities, and the benefits of declaring all gratuities.

What Qualifies as a Tip in Canada?

A tip or gratuity is defined as any payment voluntarily given by a customer to a service provider beyond the amount charged for the service itself

Tips are not legally mandatory in Canada, though they're customary in many service industries. Typically, customers provide gratuities ranging from 15% to 20% of the pre-tax bill amount, depending on the quality of service received. In some establishments, particularly for larger groups, an automatic gratuity of 15-18% might be added to the bill.

It's important to understand that, regardless of how tips are received—whether in cash, added to credit card payments, or through digital transfers—tips are considered taxable income by CRA.

image about Are tips taxable in Canada?

Types of Tips Recognized by the CRA

The CRA recognizes different categories of tips, each with specific tax implications. Understanding which type of tips you receive affects how you report them and what deductions might apply.

Direct Tips (Employee Responsibility)

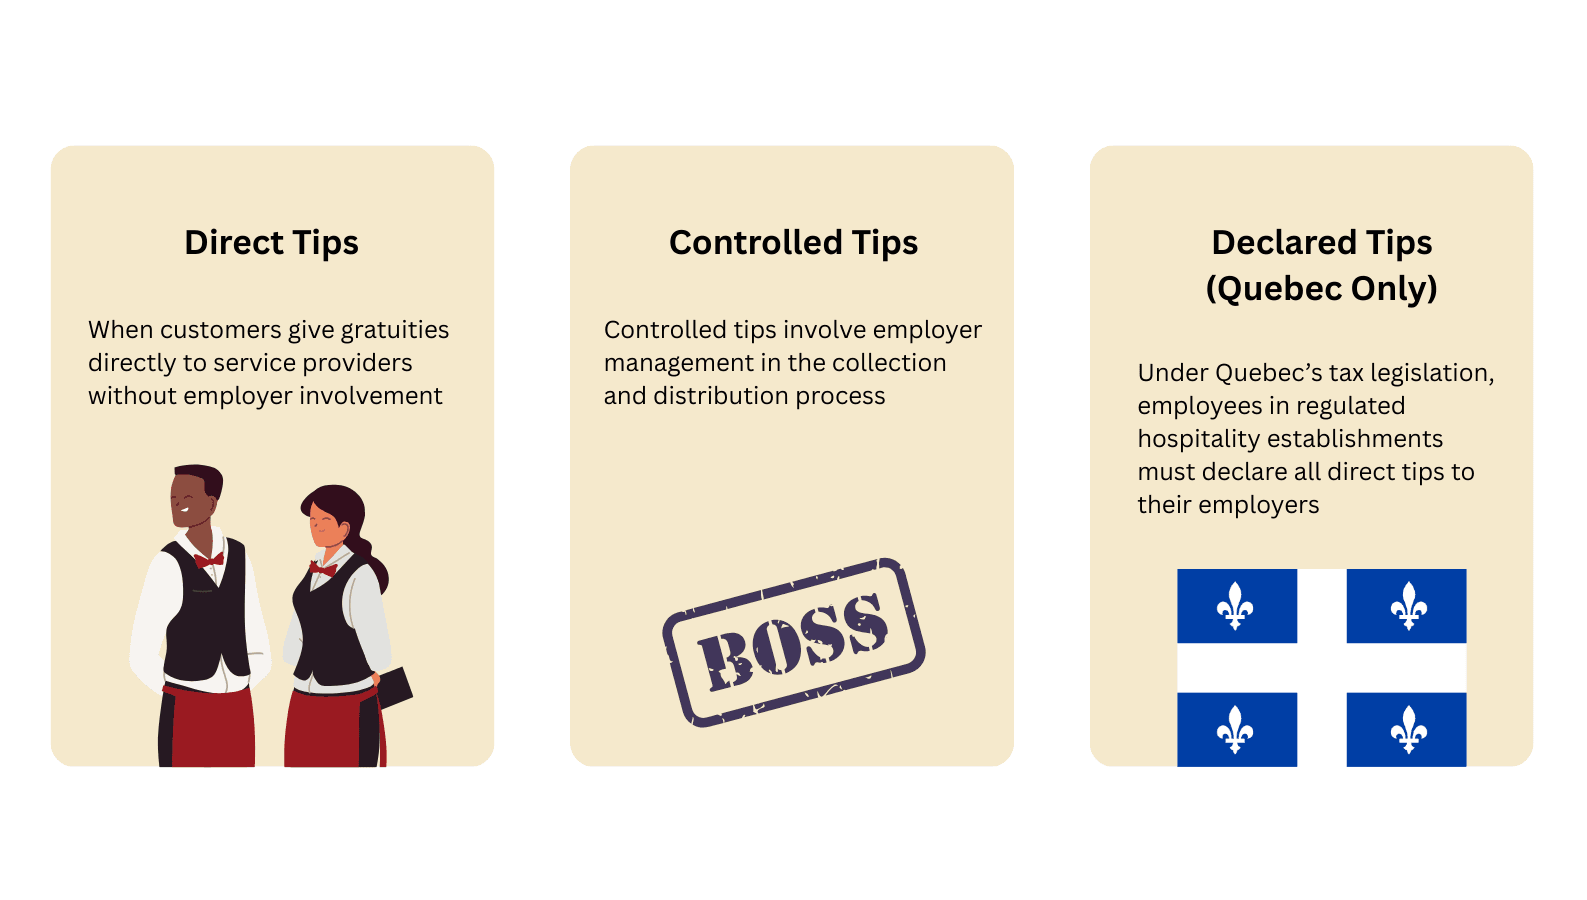
Direct tips occur when customers give gratuities directly to service providers without employer involvement. These include:

  • Cash left on tables for servers
  • Tips added to credit or debit card payments that go straight to the employee
  • Digital tips sent directly to service providers

Controlled Tips (Employer Responsibility)

Controlled tips involve employer management in the collection and distribution process. Examples include:

  • Mandatory service charges added by the establishment
  • Pooled tips that employers collect and redistribute according to a formula
  • Tips that employees turn over to employers who then distribute them
  • Automatic gratuities for large parties that the employer processes

Declared Tips (Quebec Only)

Quebec stands apart from other provinces with its unique system. Under Quebec’s tax legislation, employees in regulated hospitality establishments must declare all direct tips to their employers. Both direct and controlled tip earnings are then combined and included in the employee's insurable wages, thereby making them subject to QPP, EI and income tax accordingly. 

image about are tips taxable in Canada?

Are Tips Taxable in Canada?

Yes, all tips and gratuities are considered taxable income in Canada. The CRA expects service industry workers to report all tips received, regardless of how they were paid. 

This includes cash tips, credit card tips, and digital gratuities. Tips are subject to the same tax treatment as regular employment income, meaning they're included in your total employment income. However, depending on whether you earn controlled or direct tips, the tax implications to the employee and employer can differ. 

The taxation of tips isn't a suggestion—it's a legal requirement. Failing to report tip income can lead to serious consequences, including penalties, interest charges, and potential audits.

Employer and Employee Responsibilities for Reporting Tips

image about Are tips taxable in Canada?

Employers and employees in the service industry have specific obligations regarding the handling and reporting of tips:

Controlled Tips – Employer

With controlled tips, since these are controlled by the employer, the employer is considered to have paid these amounts to the employee. As such, employers must include controlled tips on:

  • Employees' T4 slips on box 14 as employment income
  • Withhold appropriate income tax
  • Deduct and remit CPP contributions
  • Deduct and remit EI premiums

Unlike direct tips, controlled tips are subject to CPP and EI, and hence the employers must withhold both CPP and EI before distribution.

Controlled Tips – Employee

As these are controlled by the employer, the employee has to report the amount included for tips on their T4 on Line 10100, Employment of your tax return.  

Direct Tips – Employer

With direct tips, employers generally have no reporting obligations since these gratuities pass directly from customers to employees without employer involvement. The responsibility for reporting direct tips falls entirely on the employee. Some progressive employers provide systems or tools to help employees track their tips, which can simplify tax reporting while ensuring compliance.

Direct Tips - Employee

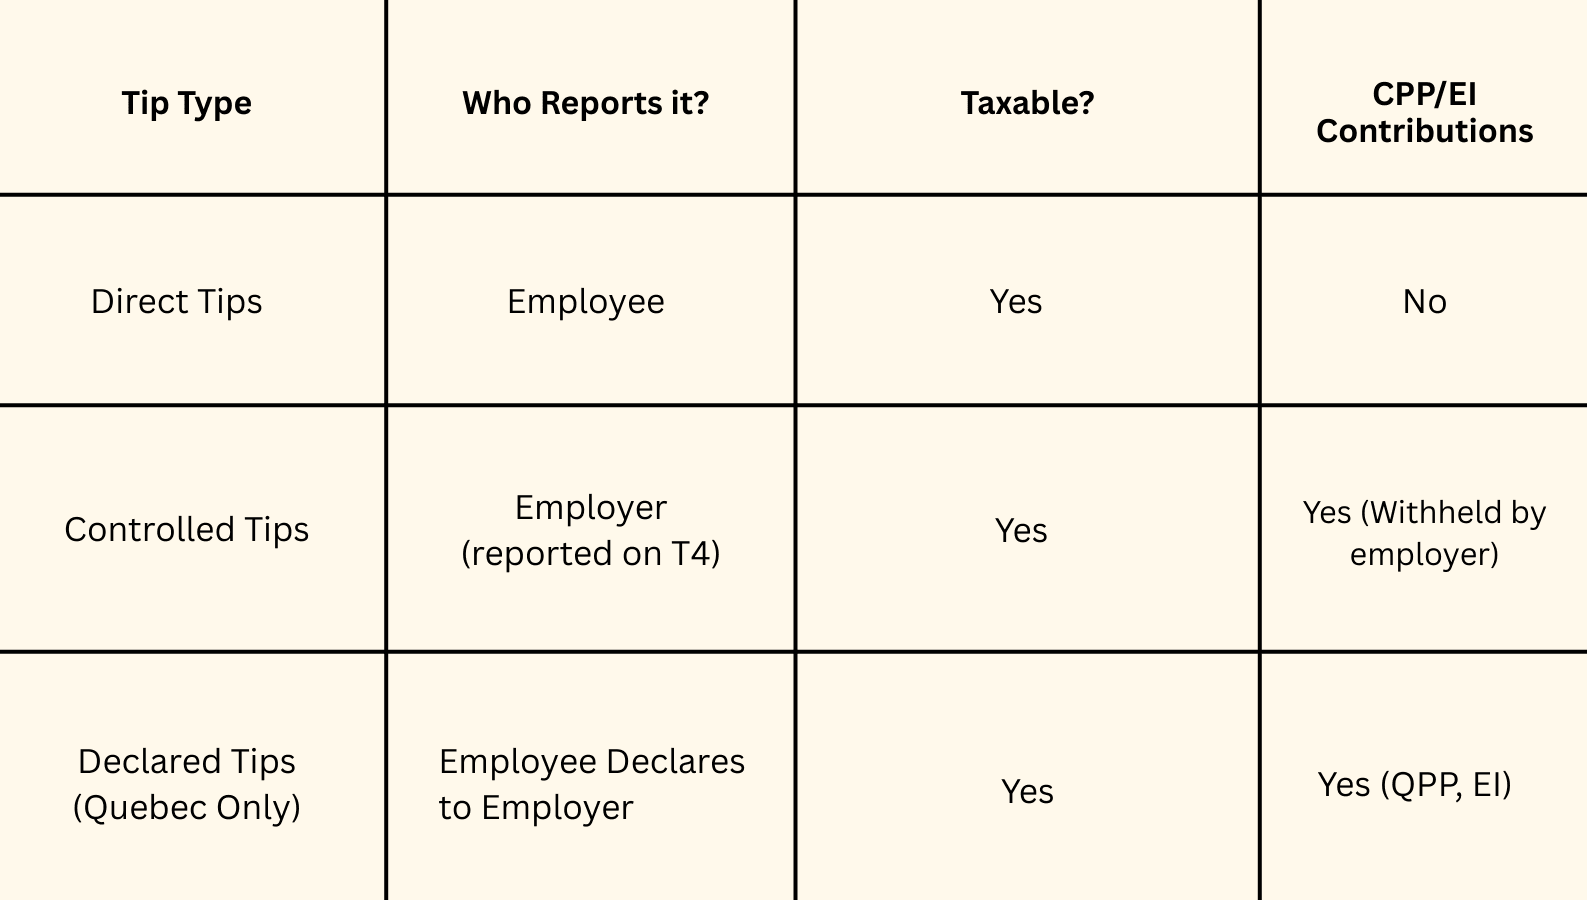
With direct tips, the employees are fully responsible for tracking and reporting direct tips on their tax returns. Generally, the employee reports these amounts on Line 10400, Employment income not reported on a T4 slip of their tax return. Further, though direct tips are considered taxable income to the employee, it is not subject to EI and CPP. 

The chart below summarizes the key differences between the various types of tips, and the tax reporting obligation of each. 

image about the different types of tips and tax reporting obligation

Why Reporting Tips Benefits You (CPP, Loans, RRSP Room)

Although it may seem tempting to underreport tip income to save on taxes, there are significant long-term advantages to declaring all gratuities. Properly reported tips increase your official income, which can improve your ability to qualify for mortgages, car loans, or even rental housing since lenders and landlords rely on documented income to assess applications. Reporting tips also directly affects your Canada Pension Plan (CPP) contributions and your Registered Retirement Savings Plan (RRSP) contribution room. For example, if you earn $500/month in tips, reporting them adds $6,000 to your official income for the year, which increases RRSP room by $1,080 (18%). Over time, this can lead to higher CPP benefits in retirement and more tax-sheltered savings opportunities.

Just as importantly, reporting tips provides peace of mind. Staying compliant with tax laws eliminates the risk of audits, penalties, and interest charges. In the long run, the financial security and opportunities that come with accurate reporting far outweigh the short-term savings of leaving tips unreported.

are tips taxable in Canada?

Consequences of Not Reporting Tips in Canada

Failing to report tips in Canada can have serious consequences. The CRA treats gratuities as taxable income, which means leaving them off your tax return could result in back taxes, daily accruing interest, and costly penalties. In cases where the CRA believes the omission was intentional or due to gross negligence, they may impose a Gross Negligence Penalty of up to 50% of the unreported income in addition to the taxes already owed.

Beyond the financial impact, not reporting tips can also increase your chances of being audited. The CRA may compare your reported income to industry averages, review your bank deposits, or even question your lifestyle to uncover discrepancies. What may seem like a small omission today could create major financial and legal stress in the future, making accurate reporting the safest and most beneficial choice.

The Bottom Line: Tips are Taxable Income in Canada

Understanding how tips are taxed in Canada is essential for service industry workers. All gratuities—whether direct or controlled—constitute taxable income that must be reported to the CRA. While it might seem advantageous to underreport tips in the short term, the potential penalties and missed benefits make compliance the wiser choice.

By keeping accurate records and reporting your tips honestly, you not only stay on the right side of the CRA but also set yourself up for long-term financial security. Whether you’re serving tables, cutting hair, driving passengers, or working in any other service role, treating your tips as legitimate income is the smartest way to protect yourself and build a stronger financial future.

If you work in the service industry and are facing CRA audit regarding your income from tips and gratuities and are looking for an accountant in Hamilton for professional guidance, contact us today. We are a full-service accounting firm in Hamilton , our experienced tax accountants are ready to provide the expertise and support you need. 
If you want to learn more about other tax and accounting topics, explore the rest of our blog!

Frequently Asked Questions

1. Do I have to report cash tips in Canada?

Yes. All cash tips are taxable and must be included on your income tax return.

2. Are tips taxed differently in Quebec?

Yes. Quebec requires employees in certain industries to declare direct tips to their employer, who includes them on the T4 slip.

3. What happens if I don’t report my tips?

The CRA may apply penalties, interest, and even audits if unreported tip income is discovered.


Disclaimer

The information provided on this page is intended to provide general information. The information does not take into account your personal situation and is not intended to be used without consultation from accounting/tax professionals. NBG Chartered Professional Accountant Professional Corporation will not be held liable for any problems that arise from the usage of the information provided on this page.
Do the New Trust Reporting Requirements Apply to You?

As the Canadian government continues to strengthen its tax reporting regulations, new requirements have been implemented for trusts which are now in effect for the year ended December 31, 2023. These changes aim to enhance transparency and ensure compliance with tax obligations. It is essential for individuals and entities involved in trust arrangements to understand these new rules to ensure compliance and avoid penalties. In this article, we will provide a comprehensive overview of the New Trust Reporting Requirements in Canada. We will explore the definition of trusts, specifically focusing on bare trusts, and discuss the reporting obligations, exemptions, penalties for non-compliance, and future planning considerations.

What is a Trust?

Before delving into the specifics of the new trust reporting requirements, it is crucial to have a clear understanding of what a trust entails. In simple terms, a trust is a legal arrangement where the ownership of assets is transferred to a trustee who manages them on behalf of beneficiaries. Thus, the trustee holds the legal title to the assets, while the beneficiaries have the beneficial ownership.

Generally, a trust exists where the following three certainties are present:

  1. Certainty of intention - the individual (settlor) who transfers title to the property to the trustee must have the intention to set up a trust. The intention can be made orally or in writing.
  2. Certainty of subject matter - the written agreement must be specific with respect to property to be transferred to the trustee.
  3. Certainty of objects - there must be certainty of either the beneficiaries or the purpose of the trust must be sufficiently certain.

Types of Trusts

The two main categories of trusts are express trusts and bare trusts.

Express Trusts

Express trusts are formal trusts established with the intention of creating a trust arrangement. These trusts are established through formal agreements such as a trust deed that outlines the terms and conditions of the trust. Express trusts include:

  • Family Trusts
  • Alter Ego or Joint Partner Trusts

Bare Trusts

Bare trusts, also known as simple trusts or informal trusts are created when the parties involved do not explicitly intend to establish a trust but inadvertently do so through their actions. Hence why they are referred to as “informal trusts”. Unlike express trusts, bare trusts do not require a formal trust deed or agreement. They are characterized by the following key features:

  1. Legal Title vs. Beneficial Ownership: The trustee holds the legal title to the trust assets, but the beneficiary retains the beneficial ownership and control. This means that the beneficiary has the right to use, enjoy, and dispose of the assets as they see fit.
  2. Principal-Agent Relationship: The relationship between the trustee and beneficiary in a bare trust is often described as a principal-agent relationship. The trustee acts as an agent for the beneficiary, carrying out transactions and managing the assets based on the beneficiary's instructions.
  3. Lack of Discretion: Unlike other types of trusts, the trustee in a bare trust does not have any independent power or discretion over the trust assets. They must act in accordance with the beneficiary's wishes and instructions.

Examples of Bare Trusts

image with text bare trust

Bare trusts can arise in various situations and have different applications in estate planning, real estate transactions, and business arrangements. Here are some common examples of bare trusts:

  1. Joint Ownership of Real Estate: It is common for parents to add their children to the legal title of their real estate as joint owners. This arrangement helps reduce probate fees upon the parents' passing and simplifies estate administration. However, the children do not have full ownership rights until their parents' passing, making this arrangement a bare trust.
  2. Bank and Investment Accounts: As parents age, they often add their children to their bank and investment accounts for ease of financial management and estate planning purposes. These accounts can be considered bare trusts as the children hold legal title to the account but are not the beneficial owners until the parents' passing. The only exemption to filing in this scenario would be if you meet the exemption of $50,000 as outlined below.
  3. Holding in Trust For Accounts: Trust arrangements where assets are held in trust for children, grandchildren, or other beneficiaries until they reach a certain age also fall under the category of bare trusts. These accounts are commonly used to protect and manage assets for minors until they become adults. The only exemption to filing in this scenario would also be if you meet the exemption of $50,000 as outlined below.
  4. Real Estate Financing: In some cases, a child may add a parent to the title of their real estate to obtain financing or other financial benefits. This arrangement creates a bare trust, with the parent acting as the trustee and the child as the beneficiary.
  5. Real Estate Transactions: It is common in real estate investments for a nominee corporation to hold the legal title of the property in trust for the beneficial owner for commercial reasons.
  6. Corporate Reorganizations: During corporate reorganizations, it is common to transfer the beneficial ownership of real estate from one taxpayer to a corporation. This arrangement can be structured as a bare trust, allowing for the transfer of ownership without triggering taxes or fees.
  7. Joint Ventures and Partnerships: Legal title for real estate or other assets held on behalf of a group of owners in a joint venture or partnership can be considered a bare trust, as the beneficiaries have the full beneficial ownership and control. The trustee acts as a custodian, holding the assets for the benefit of the individuals involved in the joint venture or partnership.

It is important to note that these examples are not exhaustive, and there may be other scenarios where a bare trust exists and requires reporting.

Understanding the New Trust Reporting Requirements

Previously, a trust was only obligated to file a T3 trust return if the trust owed income tax for the year, or if the trust realized a capital gain or disposed of capital property during the year. This meant a lot of informal trusts such as bare trusts that were created were not required to file as the trust would not owe any tax during the year.

Under the new rules, all express and bare trusts are now required to submit a T3 trust return. This means that even if a trust is inactive or has not generated income in a particular tax year, it must still fulfill the filing obligations. This expands the scope of trust reporting and aims to capture all formal and informal trusts that may have previously gone unnoticed or were exempt from filing.

In addition to the new requirement to file, detailed information is required and should be reported for each trustee, beneficiary, settlor, and any other person who can exert control or override trustee decisions concerning the allocation of the trust's income or capital (i.e advisor). This information should include:

  • Full name and address
  • Date of birth
  • Country/jurisdiction of residence
  • Taxpayer identification, for example, SIN, trust account number, business number, or a taxpayer ID used in a foreign jurisdiction

The due date for filing the trust tax return is 90 days after the end of the trust's year-end. For most trusts with a December 31st fiscal year-end, the due date for the 2023 tax year is March 30, 2024. For 2023 tax year only, the deadline has been extended to April 2, 2024.

Exemptions from Reporting Requirements

image with text exemptions

While the new trust reporting requirements apply to many bare trusts, there are certain exceptions outlined by the Canada Revenue Agency (CRA). The following types of trusts are not required to provide additional information:

  1. Trusts governed by registered plans (i.e., deferred profit sharing plans, pooled registered pension plans, registered disability savings plans, registered education savings plans, registered pension plans, registered retirement income funds, registered retirement savings plans, registered supplementary unemployment benefit plans and tax-free savings accounts) 
  2. Mutual fund trusts, segregated funds and master trusts.
  3. Lawyers' general trust accounts: Funds held in trust accounts by lawyers that are required under the professional conduct rules for a purpose that is regulated under these rules. However, if they are client-specific trust accounts (i.e client funds held in trust such as real estate proceeds, retainers, trust settlement amounts, investment funds that are administered by the lawyer on behalf of clients, withholding taxes kept in trust until the CRA provides a compliance certificate etc.), they would not meet this exemption and would fall under the new trust reporting rules. The only exception to this would be if the trust has been in existence for less than three months or it it holds less than $50,000 fair market value in assets. The new trust reporting requirements do not require the disclosure of information that is subject to solicitor-client privilege. 
  4. Graduated rate estates and qualified disability trusts: Trusts created for the benefit of individuals who have passed away or individuals with disabilities.
  5. Non-profit organizations or registered charities: Trusts that qualify as non-profit organizations or registered charities are exempt from the new reporting requirements.
  6. Trusts in existence for less than three months: Trusts that have been in existence for less than three months at the end of the year are not required to provide additional information.
  7. Trusts with assets below $50,000: Trusts that hold assets with a total fair market value of less than $50,000 throughout the taxation year are exempt from the filing requirements. The assets being held are limited to cash, government debt obligations, and listed securities such as public company shares, mutual funds and segregated funds.

It is essential to consult with a tax professional or legal advisor to determine if your trust falls within any of these exceptions and is not subject to the new reporting obligations.

Penalties for Non-Compliance

The CRA imposes penalties for late filing or non-filing of trust tax returns. The penalties can be significant and may vary depending on the circumstances. Here are some key penalties to be aware of:

  1. Late filing penalty: If the trust tax return is filed after the specified due date, a late filing penalty may apply. The penalty is generally calculated at $25 per day late, up to a maximum of $2,500 per year.
  2. Penalty for gross negligence: In cases of gross negligence, where there is a willful disregard for the reporting requirements, a penalty equal to the greater of $2,500 or 5% of the highest fair value of the trust's assets during the year may be imposed.

To avoid these penalties, it is essential to file the trust tax return on time and ensure all required information is accurately reported.

Future Planning and Considerations

To minimize future reporting obligations and streamline trust structures, there are some practical steps that can be taken:

  1. Review the purpose of the trust: Trustees should periodically review the purpose and necessity of the trust. If a trust no longer serves its intended purpose, consider winding it up or closing any in-trust accounts that are no longer necessary. By taking these steps, future reporting obligations can be reduced.
  2. Restructure existing trusts: If certain beneficiaries are no longer required or relevant, consider restructuring the trust to remove them. This can help avoid the need to disclose their information in future reporting. However, it is important to note that reporting obligations may still exist for periods during which beneficiaries were involved.

Engaging the services of a tax professional with expertise in trusts and tax planning can provide valuable guidance in ensuring proper trust structuring and compliance with reporting requirements.

Conclusion

The introduction of new trust reporting requirements in Canada has brought about significant changes in the landscape of trust administration and tax compliance. Trustees, beneficiaries, and settlors must be aware of their obligations under these new rules to ensure compliance, avoid penalties, and maintain the integrity of their trust structures.

This comprehensive guide has provided a thorough overview of the new trust reporting requirements, covering topics such as the definition and purpose of trusts, the concept of bare trusts, the detailed reporting requirements, exemptions, implications for different types of trusts, and future planning considerations.

By adhering to these requirements and maintaining ongoing compliance, trust beneficiaries and trustees can avoid penalties and ensure the smooth operation of their trusts. Trust filers are encouraged to seek professional advice to navigate the complexities of trust reporting and ensure compliance with the new rules.

If you are looking for a tax accountant to help file your trust returns under the new rules, contact us today. We are a full-service accounting firm in Hamilton that have experienced tax specialists to meet all your tax needs.

If you want to learn more about other tax and accounting topics, explore the rest of our blog!

Frequently Asked Questions

1. Is a trustee of a bare trust that owns legal title to a residential property in Canada required to also file an Underused Housing Tax (UHT) return?

Yes, the CRA interprets the word trust to include a bare trust and interprets the word trustee to include a trustee of a bare trust. Hence a trustee of a bare trust will need to file a UHT return.

2. If the trustee of a bare trust files the UHT return, do they also need to file a trust return?

Yes. Per CRA, the UHT-2900 Underused Housing Tax Return is separate from the new trust reporting regulations. Filing a UHT-2900 does not fulfill the requirement to submit a T3 Return and Schedule 15. Hence, the trust remains obligated to adhere to the new trust reporting rules.


Disclaimer

The information provided on this page is intended to provide general information. The information does not take into account your personal situation and is not intended to be used without consultation from accounting/tax professionals. NBG Chartered Professional Accountant Professional Corporation will not be held liable for any problems that arise from the usage of the information provided on this page.
How to Fix a Mistake on Your Tax Return in Canada?

Tax season can be a stressful time for many individuals and business owners. Filing your tax return accurately is crucial to avoid penalties and maximize your tax savings. However, mistakes can happen, and it's important to know how to fix a mistake on your tax return. In this article, we will walk you through the process of fixing errors on your Canadian tax return and provide a brief preview of common mistakes when filing your income tax returns.

Common Mistakes on Tax Returns

Here are some of the most common mistakes people make on their Canadian tax returns:

  • Forgetting to Claim Deductions or Credits

One common mistake is forgetting to claim all eligible deductions and credits. It can be challenging to keep track of the numerous tax deductions and credits available, especially with changing tax rules. To avoid missing out on potential tax savings, consider consulting with a professional tax accountant who can help identify applicable deductions and credits. Utilizing tax software can also assist in identifying eligible deductions and credits.

  • Failure to Transfer Unused Tax Credits

Tax credits can often be transferred to a spouse who may have insufficient income or taxes to utilize them fully. For example, unused tuition tax credits can be transferred to a parent or grandparent. Maximizing available tax credits can result in significant tax savings for families. Consulting with a tax professional can help navigate the intricacies of transferring unused tax credits.

  • Claiming Ineligible Expenses

On the flip side, some individuals mistakenly claim deductions or tax credits that are not allowed. It's crucial to understand the eligibility criteria for each deduction and credit before claiming them. For example, the Home Accessibility Tax Credit is only available for individuals who have made eligible renovations to improve accessibility in their homes.

Similarly, the deduction for student loan interest is often mistakenly claimed. Some students claim the student loan interest tax credit for payments made on personal loans, student credit, or foreign student loans, even though these expenses are not eligible. Hence, familiarize yourself with the requirements for each deduction and credit to ensure you are claiming them correctly. Ensuring accuracy and compliance with tax regulations is essential to avoid potential penalties and CRA audit triggers.

  • Inaccurate Reporting of Marital Status

Accurately reporting your marital status is crucial for determining eligibility for certain benefits and credits. If you're living with your partner in a conjugal relationship for at least 12 consecutive months or are sharing a child, you're considered common-law for tax purposes. Its important to report your marital status correctly as your marital status directly affects the benefits and credits you may be entitled to. The Canada Revenue Agency (CRA) calculates benefits such as the Canada Child Benefits, GST/HST credit, and the Working Income Tax Benefit based on your combined family income.

Reporting incorrect marital status can potentially result in the repayment of benefits received. To learn more about marital status changes, read our blog article "Importance of Informing CRA of Marital Status Change".

  • Missing the Tax Filing Deadline

Missing the tax filing deadline can have various consequences, including delayed refunds, late penalties, and interest charges. It's crucial to be aware of the deadline specific to your situation. For employed individuals, the deadline is typically April 30th, while self-employed individuals have until June 15th to file their taxes. To ensure you don't miss any 2024 tax deadlines, be sure to read our article on the various deadlines for individuals and businesses.

  • Not Filing Electronically

If you have never submitted your taxes electronically, you are overlooking numerous advantages. Firstly, it is significantly quicker and simpler compared to filing on paper. Importantly, it also offers greater accuracy. The CRA handles electronic filings with much greater speed and efficiency than paper ones, reducing the likelihood of errors that could potentially delay your refund.

How to Fix a Mistake on Your Tax Return in Canada?

How to Fix jpg

When it comes to correcting errors on your Canadian tax return, there are several methods you can use. Let's explore the different ways to request changes:

1. Online via CRA MyAccount

If you filed your tax return electronically using NETFILE or EFILE, you can make changes through the CRA MyAccount portal. Logging into your account and selecting the "Change my return" option allows you to enter the necessary adjustments. The online tool allows you to select the tax year you wish to modify and input the line numbers and corresponding figures to rectify or include information.

You cannot use the "Change my return" feature to request changes for the following:

  • Tax returns that have not been assessed yet
  • Tax returns that have been reassessed 8 times in the same tax year
  • Bankruptcy returns
  • Returns filed prior to a bankruptcy return
  • Returns filed for international or non-resident clients, even if they are considered Canadian Residents, newcomers to Canada, or individuals who left Canada during the year

You must request a change of return by mail for any of the above situations.

2. ReFile

ReFile is a service available to taxpayers who filed their returns electronically through certified software. It allows for changes to assessed returns within the last four years. However, there are exceptions to the eligibility for using ReFile. Detailed information about ReFile can be found on the CRA's website.

3. Mail

For those who prefer traditional methods, requesting changes by mail is an option. Fill out Form T1-ADJ, T1 Adjustment Request, and mail it to your local tax center. Ensure that you include copies of all supporting documents, such as receipts and slips, related to the adjustments being made. The processing time for mail-in adjustments is typically longer than online requests, ranging from several weeks to a couple of months.

The CRA Voluntary Disclosure Program (VDP)

In situations where errors or omissions on your tax return may result in penalties, the CRA has established the Voluntary Disclosure Program (VDP). This program allows taxpayers to rectify mistakes made on previously filed returns or file overdue returns without facing penalties or prosecution.

To be eligible for the Voluntary Disclosure Program, certain criteria must be met. The CRA under the new Voluntary Disclosure Program sets out the following five conditions

  1. The disclosure must be voluntary, meaning that the CRA should have no prior knowledge of the tax issue being disclosed.
  2. The disclosure must be complete, including all relevant information for the tax years affected by the error or omission.
  3. The taxpayer must owe taxes as a result of inaccurate or missing tax filings. The VDP does not apply to situations where a taxpayer is eligible for tax refunds.
  4. The tax returns being disclosed must be at least one year past the filing due date, unless part of a broader disclosure for older years.
  5. The taxpayer is required to estimate and pay the tax owing upfront as part of the disclosure process.

If you are uncertain about whether this program is suitable for you, NBG Chartered Professional Accountants can provide guidance on submitting your application under the CRA's voluntary disclosure program.

Conclusion

In conclusion, while errors on tax returns can be stressful, the Canadian tax system provides avenues for correction. Whether it's through online tools, mail-in requests, or the CRA's Voluntary Disclosure Program, taxpayers have opportunities to rectify mistakes and ensure compliance. By understanding common errors, seeking professional assistance when needed, and staying informed, you can navigate the tax filing process with confidence and peace of mind.

If you are looking for an accountant in Hamilton for professional guidance on filing your tax returns and ensuring that you are properly claiming all deductions and credits you are entitled to, contact us today. We are a full-service accounting firm in Hamilton that have experienced tax accountants to handle all your tax needs.

If you want to learn more about other tax and accounting topics, explore the rest of our blog!


Disclaimer

The information provided on this page is intended to provide general information. The information does not take into account your personal situation and is not intended to be used without consultation from accounting/tax professionals. NBG Chartered Professional Accountant Professional Corporation will not be held liable for any problems that arise from the usage of the information provided on this page.
2024 Tax Deadlines in Canada: Important Dates for Filing Your Taxes

As we step into the new year, it's crucial for individuals and businesses in Canada to stay on top of their 2024 tax deadlines. Filing taxes and meeting the deadlines set by the Canada Revenue Agency (CRA) is essential to avoid penalties and hefty interest charges. In this article, we'll walk you through the key 2024 tax deadlines for both personal and corporate taxes.

Penalties and Interest Rates for Late Tax Filings

Before we delve into the specific personal and corporate tax deadlines, we want to highlight the following:

  • Even if a taxpayer is unable to pay their balance by the due date, they should ensure to at least file their tax return by the due date. This will help you to avoid late filing penalties, which are based on the balance payable and you will only be subject to interest on the balance owing. Currently, the late filing penalty is calculated as 5% of your outstanding balance plus an additional 1% for each full month your payment is late, up to a maximum of 12 months.
  • Due to the increase in interest rates, the amount of interest charged on late or overdue balances by CRA is 10% in 2024, which is significantly higher compared to prior years. It's important to note that interest charges are not a tax-deductible expense.

2024 Tax Deadlines - Personal

Tax Deadlines for Individuals

For the calendar year 2023, the deadline to file your individual tax return (those who are not self-employed) and make payment is April 30, 2024. This deadline applies to individuals who don't report business income on their tax return. It's crucial to ensure that your tax return is filed and any balance owing is paid by this date to avoid penalties and interest charges.

Tax Deadlines for Sole Proprietors

If you or your spouse or common-law partner is a sole proprietor and reports business income on your tax return, the deadline for filing your 2023 income tax return is June 15, 2024. However, since June 15th, 2024 falls on a Saturday, the deadline to file your tax return is June 17, 2024 but any taxes owing must still be paid by April 30, 2024. This means that even if you don't have your tax return ready by April 30, 2024, you should estimate the amount of taxes owing and make the payment to avoid interest charges.

Tax instalments for Individuals

Tax instalments are another important aspect to consider when managing your tax obligations. If you are required to make tax instalments, the due dates for individuals for the 2024 tax year are:

  • March 15
  • June 15
  • September 15
  • December 15.

As a sole proprietor, if you need to make instalment payments, you will receive guidance on the payment amounts and deadlines from the Revenue Canada through mail or by accessing "my account" online.

2024 Tax Deadlines - Corporate

For small businesses operating as corporations, it's crucial to be aware of the specific 2024 tax deadlines

The deadline for filing corporate tax returns is generally 6 months after the corporation's year-end. For example, if your corporation has a year-end of December 31, 2023, the tax return filing deadline would be June 30, 2024. However, it's important to note that the filing deadline may vary based on the specific year-end date of your corporation.

In cases where the last day of the tax year is not the last day of a month, the tax return is due on the same day of the 6th month after the year-end. For instance, if your corporation's year-end is July 15, 2023, the tax return would be due on January 15, 2024.

Corporate Taxes Owing

The due dates for corporate taxes owing are earlier than the filing deadlines for tax returns. Generally, corporate taxes are due 2 months after the year-end. However, there is an exception that applies to many Canadian Controlled Private Corporation (CCPCs). If your corporation meets certain criteria, the taxes owing are due 3 months after the year-end. The criteria for the exception are as follows:

  1. The corporation is a Canadian Controlled Private Corporation.
  2. The corporation claimed the small business deduction for the current or previous year.
  3. The corporation and all associated corporations (if applicable) had taxable income less than $500,000 in the previous year.

Hence, a corporation that is a non-CCPC with a December 31st, 2023 year-end, would have to pay any balance owing on or before February 29, 2024 to avoid interest charges. If you are a CCPC, you would need to pay any balance on or before March 31st. It's important to consult with your tax accountant to ensure that you comply with the specific deadlines for your corporation's tax returns and tax payments.

Instalments for Corporations

For corporations, instalment payments are typically required if your taxes payable exceed a certain threshold. The due dates for instalment payments will depend on your filing status and previous year's tax liability. It's important to consult with your accountant or tax advisor to determine the specific instalment due dates and amounts for your corporation.

2024 Tax Deadlines - GST/HST

If your business is registered for Goods and Services Tax (GST) or Harmonized Sales Tax (HST), the specific deadlines for filing your returns and making payments will depend on whether you are a monthly, quarterly, or annual filer. The following chart illustrates the filing and payment deadlines for different types of filers.

image of 2024 tax deadlines for GST

Instalments for GST/HST Annual Filers

If your business is an annual filer for GST/HST and your net GST/HST payable for the previous fiscal year was $3,000 or more, you may be required to make quarterly instalment payments for the current fiscal year. The specific due dates and amounts will depend on your individual tax situation. It's crucial to ensure that you make these instalment payments on time to fulfill your GST/HST obligations.

Note: Monthly and quarterly GST/HST filers do not need to make instalment payments for GST/HST.

Other Tax Deadlines

RRSP Contribution Deadline

For individuals looking to contribute to their Registered Retirement Savings Plan (RRSP) for the 2023 tax year, the deadline is February 29, 2024. It's important to note that exceeding the maximum allowable contribution amount may result in penalties. Therefore, it's crucial to review your contribution limits and ensure that you stay within the prescribed limits.

T4 and T5 Deadline

For sole proprietors and corporations who pay employees via payroll, a T4 slip must be filed by February 29, 2024. For corporations who paid a dividend to their shareholder, a T5 slip must be filed by February 29, 2024. Late filing T4 or T5 slips or failing to file them all together is a $100 penalty per slip up to a maximum of $7,500.

Conclusion

Navigating the world of tax deadlines can be complex, but with the right information, you can stay on top of your obligations and avoid penalties. Whether you're an individual taxpayer or a small business owner, understanding the specific 2024 tax deadlines is crucial for maintaining compliance with the CRA. Be sure to mark these dates on your calendar and consult with a tax professional to ensure that you meet all your tax obligations.

If you are looking for an accountant in Hamilton to provide professional guidance on your filing and payment obligations, contact us.

To learn more about other tax and accounting topics, explore the rest of our blog!


Disclaimer

The information provided on this page is intended to provide general information. The information does not take into account your personal situation and is not intended to be used without consultation from accounting/tax professionals. NBG Chartered Professional Accountant Professional Corporation will not be held liable for any problems that arise from the usage of the information provided on this page.

How Do I Pay CPP and EI When Self-Employed?

‍How do I pay CPP and EI when self-employed? This is a common question often asked by self-employed individuals. Generally, two areas where self-employed individuals differ from regular employees are contributions to the Canada Pension Plan (CPP) and Employment Insurance (EI). In this article, we will walk you through the process of paying CPP and EI as a self-employed individual. We'll cover everything from who is considered self-employed to the specific contribution rates and deadlines. So, whether you're a sole proprietor, freelancer, or independent contractor, this article will provide you with the information you need to navigate the complexities of CPP and EI.

Who is Considered Self-Employed?

The Canada Revenue Agency (CRA) recognizes several types of self-employed individuals, including sole proprietors, business partners, freelancers, independent contractors, and those involved in direct sales. Essentially, if you earn income on your own outside of traditional employment, you are considered self-employed by the CRA. To determine employee vs self-employed status, its important to look at the various factors that CRA considers. If you are still unsure about your employment status, you have the option to ask CRA for a ruling, so they can determine whether you are an employee or self-employed and whether your employment is pensionable or insurable.

CPP for Self-Employed Individuals

image with text retirement and canada pension plan

CPP is a mandatory program that provides retirement income to individuals working in Canada. The amount you receive as a CPP retirement benefit when you retire is a function of how much you paid into the program during your working years. As a self-employed individual, it's important to understand your responsibilities and contributions to the CPP.

Who Needs to Contribute to CPP?

If you're between the ages of 18 and 70 and earn more than $3,500 per year, you are required to contribute to the CPP. This applies to both regular employees and self-employed individuals.

CPP Contributions - Key Differences for Self-Employed

For CPP, the key difference for self-employed individuals is the contribution rate (and corresponding contribution amount). For regular employees, CPP contributions are shared between the employee and the employer. However, as a self-employed individual, you have the responsibility of both the employee and employer contributions to the CPP. This means you'll need to contribute twice the annual percentage up to the yearly maximum.

The CPP contribution rates for self-employed individuals are subject to annual adjustments. It's essential to check the CRA website for the most up-to-date rates. For example, for the year 2023, the yearly maximum pensionable earnings (YMPE) is $66,600, and the self-employment contribution rate is 11.9%. This means that as a self-employed individual, you will contribute 11.9% of your net self-employment income, up to the maximum contribution amount of $7,508.90. To calculate your annual CPP contributions at tax time, you will need to refer to Form 5000 – Schedule 8 (CPP Contributions on Self-Employment and Other Earnings to calculate your annual contributions. Quebec residents should use Form 5005 – Schedule 8 – Quebec Pension Plan Contributions.

Please note if you are still unsure of the amount you should be contributing to your CPP, we recommend contacting a professional tax accountant.

Benefits of CPP Contributions

Contributing to the CPP has several advantages for self-employed individuals. First and foremost, it helps build a foundation for your retirement income. By making regular CPP contributions, you are securing a portion of your income for your retirement years. Additionally, contributing to the CPP has several benefits:

  1. Tax deduction: When you complete your tax return, you can claim a deduction for the "employer half" of the CPP contribution. This deduction can help reduce your overall taxable income.
  2. Federal tax credit: You are also eligible for a 15% federal tax credit for the "employee half" of the CPP contribution. This credit further reduces your tax liability.

Other Options for CPP

Self-employed individuals have some flexibility when it comes to CPP contributions. Here are some alternatives to consider:

  1. Incorporation: If you're a sole proprietor, incorporating your business provides the option to pay yourself a salary or dividends. By paying yourself a lower salary and taking the remaining income as dividends, you can reduce your CPP premiums.
  2. Pension plans: Incorporated individuals can participate in pension plans, allowing them to save for retirement while potentially reducing CPP premiums. However, it's important to note that sole proprietors do not have these options and must pay CPP premiums based on their net self-employment income.
  3. Alternative investments: Consider taking out a dividend or T4 income annually to max our your TFSA (tax-free savings account), and then use the TFSA as a replacement for your CPP. Another option is to use a corporate owned insurance policy to grow cash value on a tax-sheltered basis.

It's essential to evaluate these alternatives based on your business structure, financial goals, and long-term plans. Refer to our article that answers the question Should I Incorporate My Business that can further provide more guidance on whether incorporating is the right decision for you.

EI for Self-Employed Individuals

image with text employment insurance

While regular employees are required to pay EI premiums, self-employed individuals have the option to opt in or out of the EI benefits program. If they opt into the EI benefits program for self-employed, they have access to certain EI benefits in the event of interruption of their income. Some of these benefits include:

  1. Maternity benefits: For individuals away from work due to pregnancy or recent childbirth.
  2. Parental benefits: Available to parents on leave to care for their newborn or newly adopted child.
  3. Sickness benefits: Intended for those unable to work due to medical reasons.
  4. Family caregiver benefits for children: Available to caregivers supporting critically ill or injured individuals under 18.
  5. Family caregiver benefits for adults: Offered to caregivers aiding critically ill or injured individuals aged 18 or over.
  6. Compassionate care benefits: Reserved for caregivers tending to individuals requiring end-of-life care.

Each type of special benefit has its own maximum weekly rates of pay, as well as the maximum number of weeks you can collect the benefit. It’s important to know these maximums and you can find an easy to read chart outlining them here. Please note that the regular benefits are not availble through the self-employed program under Employment Insurance.

If you choose to opt into the EI program, you will need to register through your My Service Canada Account and pay the same EI premium rate as regular employees. EI premiums for self-employed individuals are paid annually when you file your annual Income Tax and Benefit Return using Schedule 13 (Employment Insurance Premiums on Self-Employment and Other Eligible Earnings). It's important to note that self-employed workers are exempt from paying the employer's portion of EI premiums, unlike regular employees.

Eligibility and Payment of EI Premiums

To be eligible for EI benefits as a self-employed individual, you must meet certain criteria. You must:

Another thing to keep in mind is that if you've never claimed benefits, you can opt out of the program at the end of any tax year. However, once you've claimed benefits, you'll need to continue contributing to the program as long as you're self-employed. Further, it's also crucial to note that if your business fails after paying into the system for 12 months, you will be ineligible for any benefits.

Conclusion

As a self-employed individual, understanding how to pay into the CPP and EI programs is crucial for small businesses. By contributing to the CPP, you are securing a portion of your income for retirement. Opting into the EI program provides access to specialized benefits, but it's important to weigh the benefits against the potential pitfalls and consider alternatives that align with your business and financial goals. Further, by properly calculating and remitting CPP/EI contributions, self-employed individuals can ensure compliance with their payroll remittances and maximize their benefits.

Remember, this guide is intended to provide general information and should not replace personalized advice from a qualified tax professional. If you’re still unsure and are looking for an accountant in Hamilton to provide professional guidance, contact us.

If you want to learn more about other tax and accounting topics, explore the rest of our blog!


Disclaimer

The information provided on this page is intended to provide general information. The information does not take into account your personal situation and is not intended to be used without consultation from accounting/tax professionals. NBG Chartered Professional Accountant Professional Corporation will not be held liable for any problems that arise from the usage of the information provided on this page.